
Intangible Asset Valuation MCP Server
Intangible asset valuation: 14 tools, 124+ formulas for IP, technology, goodwill, PPA, impairment.
Connector by ascent-partners.com · Domain verified by the MCP Registry
Install
Works with Claude Code, VS Code, Codex, Cursor, Windsurf, Claude Desktop. Read the repository before you give any tool access to your data.
npx agentmarket install connector/ascent-partners-com-intangible-valuation
Asks which of your tools to add it to (Claude Code, Codex, Cursor, VS Code, Windsurf, Gemini CLI, Claude Desktop) and shows the change first. See https://agentmart.dev/cli.
Remote endpoint
https://intangible-valuation.ascent-partners.com/api/mcpRemote (HTTP)
Get the weekly diff
The weekly diff: one email a week with new agent tools, notable updates and grade changes, plus security alerts for tools you follow. Double opt-in, one-click unsubscribe.
About
Reviews
Write a reviewNo reviews yet. Installed it? Reviews come from verified installers only. How reviews work
Permissions
What this server can do and what it asks for, from its tool list, install config and code. Checked Oct 25, 2026.
- Tools
- 14 read · 0 write · 0 deleteRead-only
- Secrets
- None asked for
- Install scripts
- None found
- Runs as
- Python package
Tools by what they do 14
From the running server's own tool list (tools/list) on Oct 25, 2026.
Read 14 · Look things up without changing anything.
valuation_compliancevaluation_cost_approachvaluation_customervaluation_discount_ratevaluation_goodwill_ppavaluation_human_capitalvaluation_impairmentvaluation_income_methodsvaluation_ipvaluation_market_approachvaluation_royalty_analysisvaluation_simulation
Show 2 more tools
valuation_technologyvaluation_time_value
Network hosts it talks to 25
amazon.com· found in codeapi.deepseek.com· found in codeapi.github.com· found in codeapi.stlouisfed.org· found in codeasc.fasb.org· found in codeascent-partners.com· found in codecontext7.com· found in codeeodhd.com· found in codefred.stlouisfed.org· found in codegithub.com· found in codeglama.ai· found in codehkexnews.hk· found in codeiaasb.org· found in codeifrs.org· found in codeintangiable-valuation.vercel.app· found in codeintangible-valuation.ascent-partners.com· found in remote endpoint, install command, codeinterbrand.com· found in codeivsc.org· found in codektmine.com· found in codeopencode.ai· found in codepages.stern.nyu.edu· found in coderaw.githubusercontent.com· found in coderoyaltysource.com· found in codestooq.com· found in codewipo.int· found in code
Tools (14)
As the server listed them on Oct 25, 2026. Descriptions are the server’s own words; hidden characters are shown as [U+…].
valuation_complianceTransfer Pricing & Litigationread-onlyTransfer pricing and litigation: the Comparable Uncontrolled Price arm's-length range and patent infringement damages with pre-judgment interest. Method selects the formula. Use for OECD transfer-pricing pricing of intercompany intangibles and for patent infringement damages awards. For royalty-rate benchmarking to set a rate use valuation_royalty_analysis; for the substantive asset valuation use valuation_ip or valuation_income_methods. Per method: cup_transfer_price needs controlled_price + uncontrolled_prices; patent_infringement_damages needs lost_profits_or_royalty + infringement_period +…
valuation_cost_approachCost Approachread-onlyCost approach: depreciated reproduction cost from a cost breakdown and depreciated replacement cost with equivalent utility, both reduced by obsolescence. Method selects the formula. Use when no income or market evidence exists, or to corroborate income and market indications for internally developed intangibles. For income-based indications use valuation_income_methods; for market evidence use valuation_market_approach. Per method: reproduction_cost needs development_costs (optional: obsolescence_factors); replacement_cost needs current_cost (optional: obsolescence_factors). obsolescence_fact…
valuation_customerCustomer-Related Assetsread-onlyCustomer-related intangibles: customer relationships with attrition, distribution networks by channel profitability, and non-compete agreements on protected profits. Method selects the formula. Use for customer relationships, distribution networks, and non-compete assets; customer_relationships projects multi-period revenue with a retention rate. For the workforce and key-person assets use valuation_human_capital; for technology assets use valuation_technology. Per method: customer_relationships needs customer_count + avg_revenue_per_customer + retention_rate + profit_margin + discount_rate + …
valuation_discount_rateDiscount & Capitalization Ratesread-onlyConstruct discount and capitalization rates: build-up, CAPM, WACC, tax-amortization benefit, control premium, Finnerty DLOM, and currency/country-risk adjustment. Method selects the formula. Use to derive the rate that feeds every income-based method; build_up and capm estimate cost of equity, wacc blends debt and equity. For a cross-border rate with currency and country premia use method currency_adjusted; for the cash flows the rate discounts use valuation_time_value. Per method: build_up needs risk_free_rate + equity_risk_premium (optional: size_premium, industry_risk_premium, specific_risk…
valuation_goodwill_ppaGoodwill & Purchase Price Allocationread-onlyGoodwill and purchase price allocation: goodwill as the residual, a full PPA waterfall across identified intangibles, and useful-life estimation. Method selects the formula. Use for ASC 805 / IFRS 3 business combinations; purchase_price_allocation allocates consideration to identified intangibles with the remainder to goodwill. For subsequent goodwill and intangible impairment testing use valuation_impairment; for individual intangible fair values feed valuation_ip, valuation_technology or valuation_customer into the allocation. Per method: goodwill needs purchase_price + fair_value_net_identi…
valuation_human_capitalHuman Capitalread-onlyHuman capital: assembled-workforce value by replacement cost and key-person value from revenue contribution and departure risk. Method selects the formula. Use for assembled workforce and key-person intangibles; assembled_workforce nets training and attrition into a replacement cost. For customer-related assets use valuation_customer; for technology assets use valuation_technology. Per method: assembled_workforce needs employee_count + avg_replacement_cost + training_cost + productivity_factor + attrition_rate; key_person needs revenue_contribution + replacement_cost + departure_probability + …
valuation_impairmentImpairment Testingread-onlyImpairment testing: goodwill impairment and intangible impairment under US GAAP (ASC 350) or IFRS (IAS 36). Method selects the formula. Use for annual or triggering-event impairment testing; goodwill_impairment compares a reporting unit's carrying value with its fair value. To compute the initial goodwill or allocation use valuation_goodwill_ppa; for the underlying asset fair values use the relevant asset-type tool. Per method: goodwill_impairment needs carrying_value + fair_value (optional: reporting_unit, standard); intangible_impairment needs carrying_value (optional: fair_value, recoverabl…
valuation_income_methodsIncome Methodsread-onlyIncome approach: relief from royalty, multi-period and single-period excess earnings, incremental cash flow, and contributory asset charges. Method selects the formula. Use for the income-approach arithmetic: relief_from_royalty for IP with observable royalty rates, and excess earnings (mpeem or single_period_excess_earnings) for the residual intangible. For a complete asset-specific valuation of customer, technology, IP or workforce assets, prefer the dedicated valuation_customer, valuation_technology, valuation_ip and valuation_human_capital tools. For royalty-rate inputs use valuation_royal…
valuation_ipIntellectual Propertyread-onlyIntellectual property: risk-adjusted patent value, trademark/brand value, copyright income value, and trade-secret value under secrecy risk. Method selects the formula. Use to value a specific IP right; patent weights projected cash flows by probability of success, trademark uses brand strength to set the royalty. For technology, software, data, and platform assets use valuation_technology; for customer and workforce assets use valuation_customer and valuation_human_capital. Per method: patent needs remaining_life + cash_flow_projections + probability_of_success + discount_rate (optional: comp…
valuation_market_approachMarket Approachread-onlyMarket approach: value from comparable transaction revenue multiples or capitalize a royalty stream into a perpetuity value. Method selects the formula. Use when reliable comparable transactions or royalty rates exist for the subject asset. For income-based excess earnings use valuation_income_methods; for royalty-rate selection and adjustment use valuation_royalty_analysis. Per method: comparable_transactions needs comparables + subject_revenue (optional: adjustments); royalty_capitalization needs revenue + royalty_rate + discount_rate. Each comparable is {revenue, multiple}; comparable_trans…
valuation_royalty_analysisRoyalty Rate Analysisread-onlyRoyalty analysis: benchmark royalty-rate ranges by IP type and industry, adjust a base rate for deal factors, and apply the 25% rule of thumb. Method selects the formula. Use to select and support a royalty rate before a relief-from-royalty or royalty-capitalization valuation. To apply the chosen rate in a valuation use valuation_income_methods (relief_from_royalty) or valuation_market_approach (royalty_capitalization); for transfer-pricing pricing use valuation_compliance. Per method: benchmark needs ip_type + industry (optional: comparable_database); adjust needs base_royalty_rate + adjustme…
valuation_simulationUncertainty & Sensitivityread-onlyUncertainty analysis: Monte Carlo valuation, Monte Carlo sensitivity ranking, decision-tree expected values, and one-at-a-time sensitivity analysis. Method selects the formula. Use to quantify and stress the uncertainty around a point valuation; monte_carlo simulates all listed inputs, monte_carlo_sensitivity ranks the drivers. For a single deterministic point value use the relevant valuation tool; sensitivity_analysis varies one parameter of a core function only. Per method: monte_carlo needs input_distributions (optional: iterations, seed); monte_carlo_sensitivity needs base_params + distrib…
valuation_technologyTechnology Assetsread-onlyTechnology assets: developed technology under life-cycle risk, software under cost and income, data assets with a quality adjustment, and platforms with network effects. Method selects the formula. Use for developed technology, software, data, and platform intangibles; developed_technology and software blend cost and income evidence. For patents, trademarks, copyrights, and trade secrets use valuation_ip; for customer relationships use valuation_customer. Per method: developed_technology needs rd_costs + life_cycle_stage + competitive_advantage + discount_rate + cash_flow_projections; software…
valuation_time_valueTime Value of Moneyread-onlyTime value of money: discount or compound a single sum, value level and growing annuities and perpetuities, and compute a terminal value by Gordon growth or exit multiple. Method selects the formula. Use to move cash flows through time or to value a terminal value in a DCF; combine with a rate from valuation_discount_rate. For uneven multi-period cash flows use valuation_income_methods; for rate construction use valuation_discount_rate. Per method: present_value needs future_value + discount_rate + periods; future_value needs present_value + discount_rate + periods; annuity_pv needs payment + …
Signals
- Stars
- 1
- Forks
- 1
- Open issues
- 0
- Weekly downloads
- 92
- Last commit
- Oct 23, 2026 (6 days ago)
- Last release
- Oct 14, 2026 (15 days ago)
- Last package publish
- Oct 14, 2026 (15 days ago)
From GitHub (fetched Oct 24, 2026) and the package registry.
Details
- Registry name
com.ascent-partners/intangible-valuation- Version
- 2.1.4
- Auth
- Auth not stated
- Packages
- pypi intangible-valuation
- License
- MIT
- First seen
- Oct 24, 2026
- Last checked
- Oct 25, 2026
More from ascent-partners.com
- 0.586score
HKEx Filings
ascent-partners.com
Live HKEx (Hong Kong Stock Exchange) regulatory filings for AI agents.
ConnectorAFreshness: ARemoteLocalRead-only★ 16↓ 60/wkClaude Code +5 - 0.568score
Startup Valuation MCP Server
ascent-partners.com
Startup valuation for AI agents: 14 tools, 80+ pre-revenue formulas.
ConnectorAFreshness: ARemoteLocalRead-only★ 3↓ 71/wkClaude Code +5 - 0.559score
Fair Value MCP Server
ascent-partners.com
Valuation MCP: DCF/NAV/CCA, WACC, derivatives, credit risk, fixed income, structured products.
ConnectorAFreshness: ARemoteLocalRead-only★ 1↓ 74/wkClaude Code +5 - 0.543score
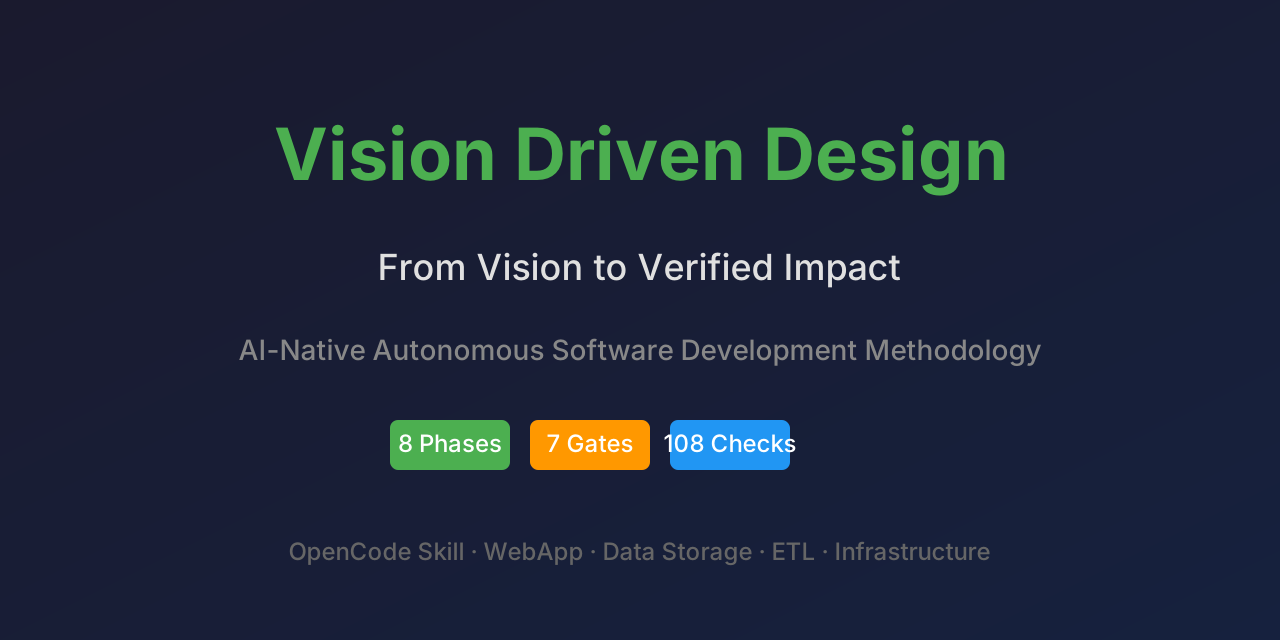
Vision Driven Design (VDD) MCP Server
ascent-partners.com
Spec-driven development MCP server: 8 phases, bi-directional traceability, 7 quality gates.
ConnectorAFreshness: ARemoteLocalRead-only★ 2Claude Code +5 - 0.534score
ESG Hub MCP Server
ascent-partners.com
ESG knowledge base for AI agents: hybrid search, glossary, frameworks, industries, graph traversal.
ConnectorAFreshness: ARemoteLocalRead-only★ 1Claude Code +5 - 0.524score
Opencode Workbench
ascent-partners.com
Provision an OpenCode workbench and MCP stack on any Linux box, local or over SSH.
ConnectorAFreshness: ARemoteLocal★ 1Claude Code +5
Cite this page
Intangible Asset Valuation MCP Server. Agent Mart. https://agentmart.dev/connectors/ascent-partners-com-intangible-valuation (last updated 2026-10-25)